Does home insurance cover water damage in Ontario?
It depends on where the water came from, and on what was added to the policy before it arrived. What the Insurance Bureau of Canada says, and why the photographs come before the fans.
Water on the floor now? Call 647-697-7435, answered 24 hours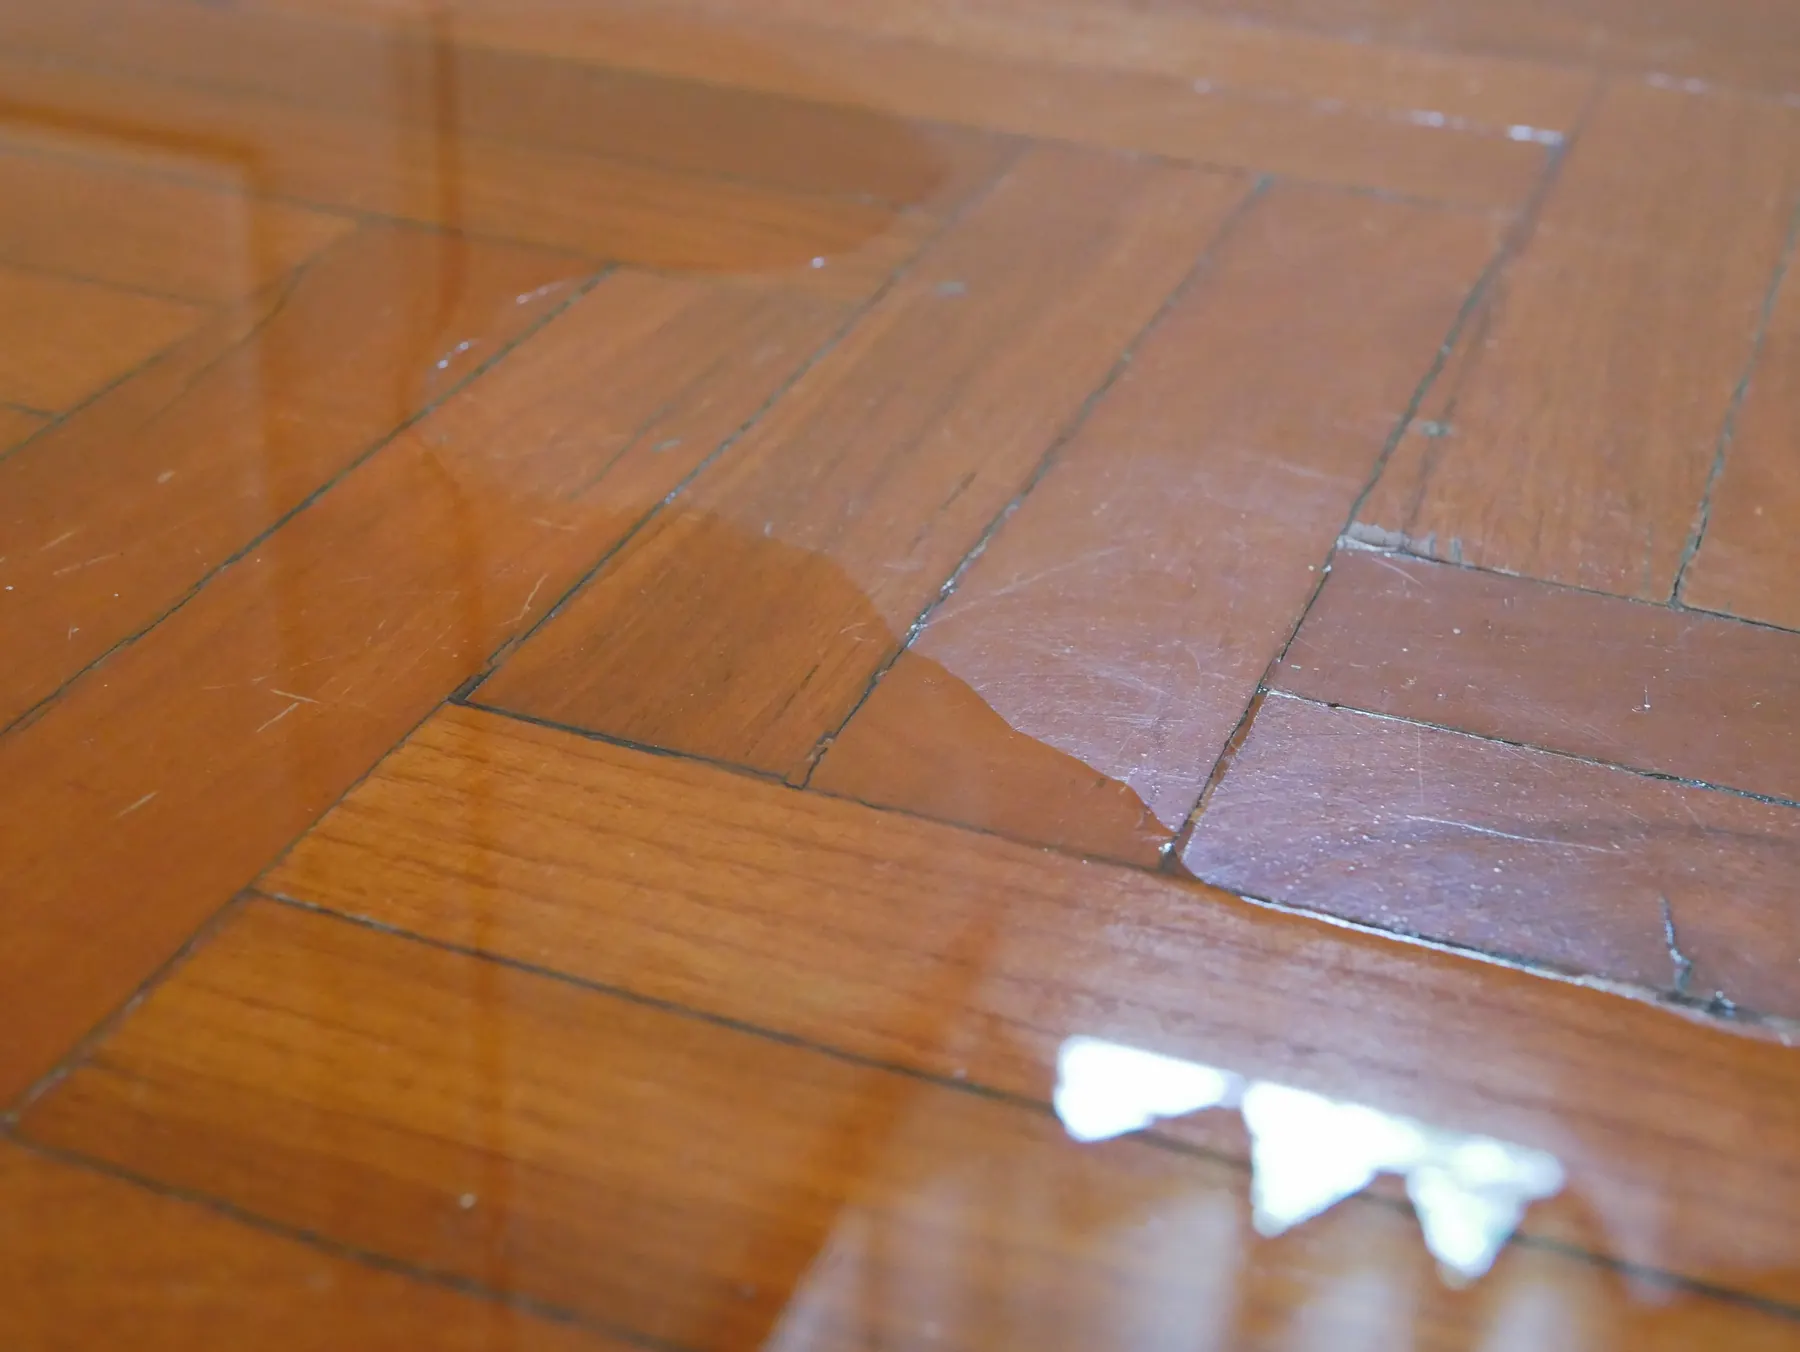
Often, but it depends on the source. The Insurance Bureau of Canada says home policies usually include sudden and accidental escape of water from plumbing, appliances or a water main. Sewer backup and overland flood are optional coverages that must have been added. Your own policy and your insurer decide.
This is general information, not insurance advice. Policies differ. The wording of yours is what counts.
What is usually covered
The Insurance Bureau of Canada's guide to home insurance coverage describes water damage cover as usually including damage from the sudden and accidental escape of water from an indoor plumbing, heating, sprinkler or air conditioning system, from an indoor or outdoor domestic appliance on your premises, or from a water main.
In practical terms that is the burst supply line, the failed water heater, the washing machine hose that lets go. The words that matter are "sudden and accidental". They are the insurer's test, and they are why the timeline of what you found and when is worth writing down.
What is optional, and what is commonly left out
The same IBC guide says coverage for overland flooding or sewer backup may be available as an optional add-on. Its flooding and insurance page is more direct on two points. Flood coverage is optional and typically covers things like the overflow of lakes, ponds or rivers and surface water from heavy rainfall or melting snow. And water damage in a basement due to a sewer backup is only covered if you have purchased specific, optional sewer backup coverage.
| Where the water came from | What the IBC says |
|---|---|
| Sudden, accidental escape from plumbing, an appliance or a water main | Usually included in home policies |
| Sewer backup into the basement | Only with specific, optional sewer backup coverage |
| Overland water: rivers, heavy rain, melting snow across the ground | Optional flood coverage |
| Groundwater and seepage | Typically not standard across all home policies |
| Freezing of indoor plumbing | Generally regarded as preventable. Precautions are expected if you are away |
On freezing, the IBC notes that homeowners away for an extended period are expected to take precautions, such as draining the pipes, to keep that cover. It also notes that additional coverage for roof ice damming may be available for purchase.
The uncomfortable part is that two of the common ways a basement fills, a sewer backup in a storm and water coming in over the ground, are both on the optional side of that table. The time to find out which ones you bought is today. Read the declarations page, or ask your broker in writing.
Why you document before you dry
Drying destroys evidence. That is its purpose. A floor that was under water on Tuesday looks ordinary by Friday, and a claim then rests on what you remember.
The IBC's advice after a flood is to make a complete list of all damaged, destroyed or lost items, take photos of them, keep all receipts related to clean-up, and report the claim to your insurance representative as soon as possible. The City of Toronto's basement flooding guidance says much the same: photos of the damage, and receipts from emergency repair or clean-up work.
So the order is:
- Stop the water and make the area safe. Nobody expects you to leave a pipe running for the sake of a photograph.
- Photograph and video everything as it is. Wide shots from each doorway, the water line on walls and furniture legs, the failed part, the source.
- Report the claim. Ask what the insurer wants kept, and whether they need to see anything before it is removed.
- Start extraction and drying. Do not wait days for a visit while the walls soak. Ask your insurer, when you report the claim, what they expect you to do to limit further damage, and note the answer.
- Keep damaged items, or photograph them before they go out. Keep every receipt.
The first three can happen inside an hour. The step by step version is in the first hour of a water leak.
What a restoration company adds to a claim
A phone camera records what the room looked like. It does not record how wet the inside of a wall is. Restoration work can produce a second kind of evidence: a record of which materials were wet and how far, what was removed and why, and what drying equipment ran and for how long.
AllCleaner can document water damage for an insurance claim, and that record is made as the work goes, not reconstructed afterwards. What it cannot do is tell you whether the claim will be paid. That is between you, your policy and your insurer, and anyone in the trade who promises otherwise is guessing.
If the cover is not there, the work is still the same work. The published ranges are in what water damage restoration costs in Toronto, and the figure is confirmed before anything starts.
For a leak or a flood, AllCleaner's water damage cleaning and restoration covers extraction, drying and the documentation. The line is answered 24 hours on 647-697-7435.
Short answers.
- Does home insurance cover a burst pipe in Ontario?
- Usually. The Insurance Bureau of Canada says home policies usually include damage from the sudden and accidental escape of water from indoor plumbing, heating, sprinkler or air conditioning systems, a domestic appliance, or a water main. Your own policy wording and your insurer decide what is covered in a particular claim.
- Is sewer backup covered by home insurance?
- Not automatically. The Insurance Bureau of Canada says water damage in a basement due to a sewer backup is only covered if you have purchased specific, optional sewer backup coverage. Check your policy or ask your insurance representative whether that coverage was added.
- Should I start drying before the insurance adjuster comes?
- Stop the water and make the area safe at once, and report the claim as soon as possible. Photograph everything before it is moved or dried, because drying removes the evidence. A restoration company can record the damage while the emergency work is done.